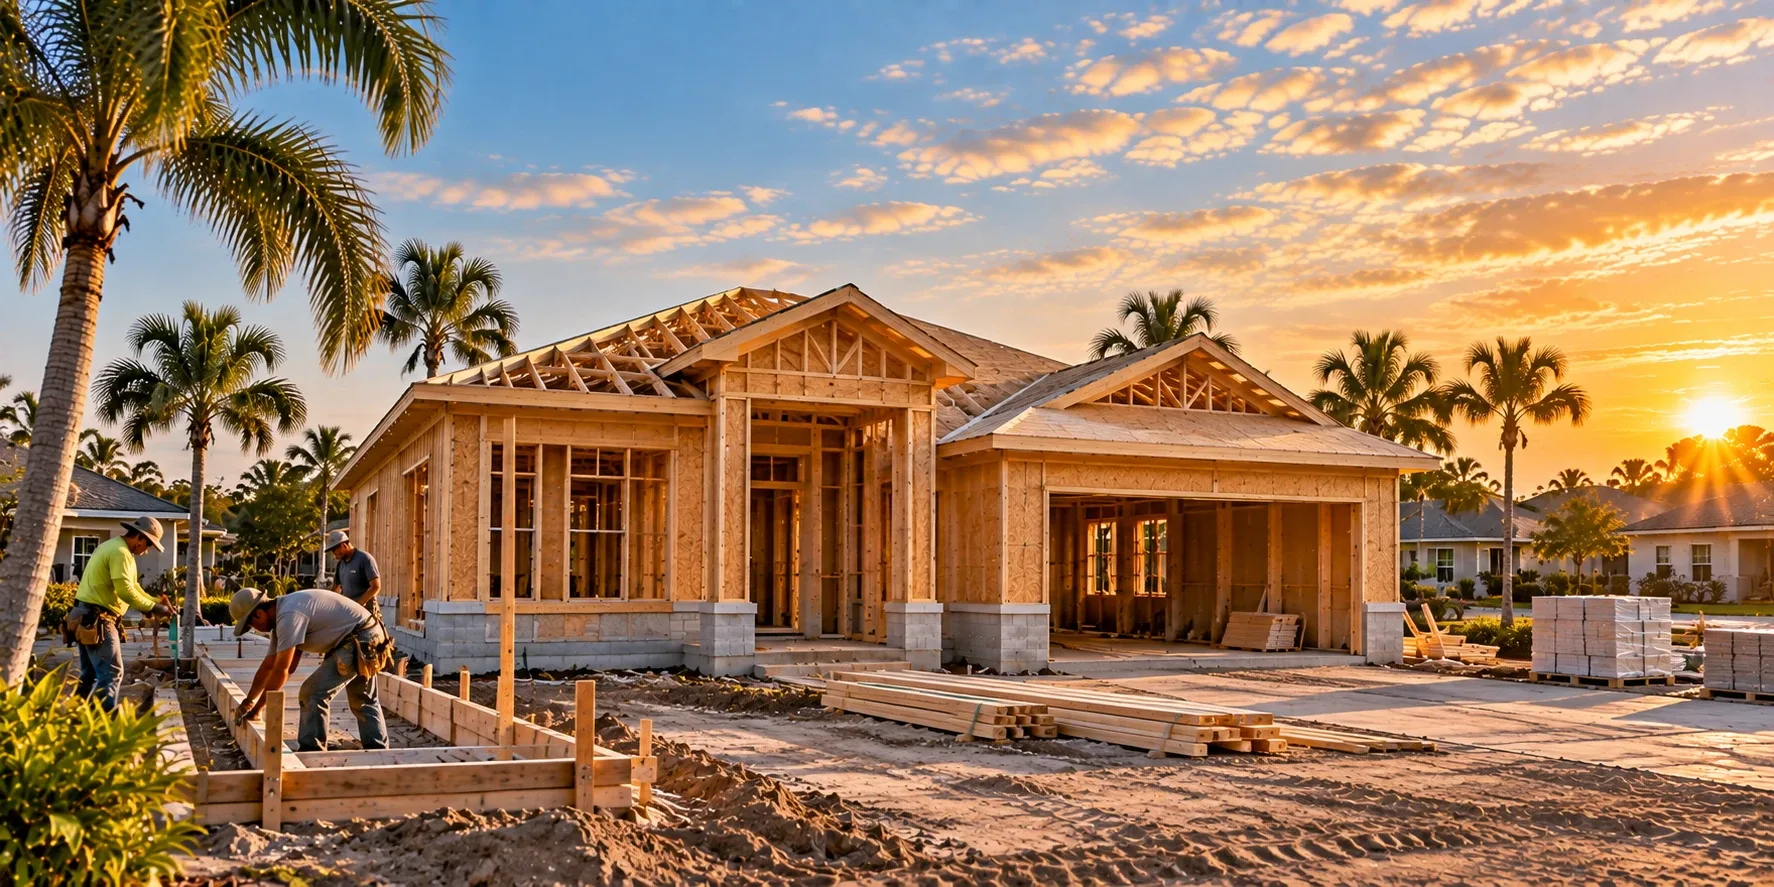
New single-family home framed during construction at sunset

Loans › New Construction Loans

New Construction

Ground-up residential financing

Construction loans for builders and investors. Finance land acquisition and vertical construction through a single facility with draw-based funding released as milestones are completed. From spec homes to small multifamily.

Close in as few as 10 days

Up to 85% loan-to-cost

100% of construction budget funded through draws

Get your construction loan quote

Term sheet in 24 hours. No obligation.

No credit pull required. Your information is secure.

$150K-$3M

Loan size

Up to 85%

LTC

Up to 70%

Max LTV

From 10%

Rate

12-24 mo

Term

10 days

Fastest close

All loans are subject to underwriting approval. Rates, terms, and fees vary based on property type, loan-to-value ratio, borrower experience, and market conditions. Requity Lending is a commercial bridge lender; we do not offer consumer residential mortgages. Contact us for a customized quote.

Why Requity

Built for builders who break ground

Single-Close Simplicity

One loan covers both land acquisition and vertical construction. No need to coordinate separate land loans and construction facilities. One closing, one set of documents, and one point of contact from dirt to certificate of occupancy.

Milestone-Based Draw Process

Construction funds are released as phases are completed: site work, foundation, framing, mechanicals, and finish. Third-party inspections verify progress and funds are wired within 2-3 business days of approval. Interest is charged only on the drawn balance.

Flexible Exit Strategies

Sell the completed home at market value, refinance into a long-term DSCR rental loan, or list and hold. Your exit plan can evolve as the market shifts during construction.

Use Cases

What we finance

From single-family spec homes to small multifamily builds and accessory dwelling units. Every ground-up project has a loan structure to match.

01

Spec Home Builds

Build single-family homes for resale in high-demand markets. Finance the lot purchase and full construction cost through a single facility, then sell the completed home to an end buyer. Ideal for experienced builders targeting move-in-ready inventory in supply-constrained neighborhoods.

02

Infill & Lot Development

Develop vacant infill lots, subdivided parcels, or teardown-and-rebuild opportunities in established neighborhoods. These projects benefit from strong comparable sales, existing infrastructure, and buyer demand for new construction in areas where inventory is limited.

03

Small Multifamily Construction

Ground-up duplexes, triplexes, and fourplexes built as investment properties. Finance the full construction and hold or sell upon completion. Small multifamily new builds generate strong rental income and command premium valuations in markets with housing shortages.

04

Townhome Projects

Small-scale townhome developments of 2-4 attached units per building. Townhomes offer efficient land use and strong buyer appeal for entry-level homeownership. Construction financing covers site work through finish with draws tied to each phase of the build.

05

ADU & Detached Unit Construction

Build accessory dwelling units on existing residential lots where zoning permits additional density. ADUs generate rental income, increase property value, and are increasingly popular in markets with housing affordability pressures and favorable local regulations.

06

Land Acquisition + Build

Finance the land purchase and construction in a single facility. Acquire a buildable lot, break ground, and complete construction under one loan with one closing. Eliminates the need for a separate land loan and simplifies the capital stack for ground-up projects.

Eligibility

Who qualifies and what you need

New construction loans are for investment properties only, not owner-occupied residences. Both first-time builders and experienced developers can qualify with the right deal and team.

Eligible Property Types

We finance ground-up residential construction across a range of property types and markets.

Single-family homes (SFR)

2-4 unit residential properties

Townhomes

Accessory dwelling units (ADUs)

Infill lots with approved plans

Urban, suburban, and select rural markets

Borrower Requirements

We underwrite the project first, then the builder. Experience and a licensed GC are key factors.

Prior construction or renovation experience preferred

First-time builders considered with strong deal and GC partnership

Licensed general contractor required (borrower or third-party)

LLC or corporate entity required

What to Bring

A complete deal package helps us deliver a term sheet within 24 hours.

Property address or lot information with purchase price

Construction plans and permits (or timeline to obtain)

Detailed construction budget with line-item breakdown

General contractor agreement and license

Comparable sales for completed value estimate

Draw Process

How construction draws work

Your construction budget is held in escrow and released as phases are completed. The process is straightforward: finish the phase, request the draw, get paid.

01

Submit Plans & Budget

Provide your construction plans, permits, and a detailed line-item budget with your loan application. Our team reviews the build plan and structures a draw schedule around major construction phases: site work, foundation, framing, mechanicals, and finish.

02

Complete Phase & Request Draw

Finish a construction milestone and submit a draw request through our portal. Upload progress photos and documentation for the completed phase. Draw requests can be submitted at any point as milestones are reached.

03

Third-Party Inspection

A licensed inspector verifies that the completed work matches the approved plans and budget. Inspections are typically scheduled within 1-2 business days of your draw request to keep the project moving.

04

Funds Released

Once the inspection confirms the phase is complete, funds are wired to your account within 2-3 business days. Interest is calculated only on the drawn balance, so you pay nothing on future construction phases until they are funded.

FAQ

New construction lending FAQ

What is a new construction loan?

A new construction loan is a short-term financing facility designed for building residential properties from the ground up. The loan covers both the land acquisition and the vertical construction costs. Funds are released in phases through a draw process as construction milestones are completed, and interest is charged only on the amount that has been drawn. Terms are typically 12 to 24 months, giving the builder time to complete construction and sell or refinance the finished property.

How much can I borrow for a new construction project?

Requity Lending provides new construction loans from $150,000 to $3,000,000. We lend up to 85% of the total project cost (land price plus construction budget) and up to 70% of the completed value. The construction portion of the loan is funded at 100% of the approved budget and released through draws as phases are completed and inspected.

Do I need construction experience to qualify?

Prior construction or real estate investment experience is preferred but not always required. Builders with a track record of completed ground-up projects will receive the best terms and fastest approvals. First-time builders can qualify with a strong deal, a licensed general contractor, adequate reserves, and a realistic construction timeline and budget.

How does the construction draw process work?

After closing, construction funds are held in escrow and released as milestones are completed. The draw schedule is structured around major phases: site work, foundation, framing, mechanicals (electrical, plumbing, HVAC), and finish (drywall, flooring, fixtures, landscaping). You submit a draw request through our portal, a third-party inspector verifies the work, and funds are wired within 2-3 business days of a successful inspection.

How fast can Requity close on a new construction loan?

We can close new construction loans in as few as 10 business days from signed term sheet. Timeline depends on the completeness of your application package, including approved plans, permits, and a detailed construction budget. We deliver term sheets within 24 hours of receiving a complete deal package, and there is no credit pull required to receive a term sheet.

Do I need approved plans and permits before applying?

You do not need approved plans to receive a term sheet or begin the underwriting process. However, approved plans and permits are required before closing. If you are in the planning or permitting phase, we can issue a conditional term sheet based on preliminary plans and close once approvals are in place. Early engagement helps us move quickly once permits are secured.

Can I be my own general contractor?

In most cases, a licensed general contractor is required to manage the construction project. If you hold a valid general contractor license in the state where the property is located, you may serve as your own GC. Unlicensed borrowers will need to engage a licensed third-party general contractor. The GC agreement and license are part of the required loan documentation.

What happens if construction costs exceed the original budget?

Cost overruns are common in construction. If your project exceeds the approved budget, we evaluate the situation on a case-by-case basis. Options may include a loan modification to increase the facility, reallocation of contingency funds within the existing budget, or additional borrower equity contribution. We recommend building a contingency buffer of 10-15% into your original construction budget.

Can I finance land and construction in one loan?

Yes. Our new construction loan covers both the land acquisition and the full construction budget in a single facility with one closing. You do not need a separate land loan. The land portion funds at closing and construction draws are released as phases are completed. This simplifies the capital stack and reduces total closing costs compared to a two-loan structure.

What types of properties can I build with a construction loan?

Requity finances ground-up construction of single-family homes, duplexes, triplexes, fourplexes, townhomes, and accessory dwelling units (ADUs). Properties must be residential and located in markets with demonstrated demand for new construction. We do not finance large-scale subdivisions, commercial buildings, or owner-occupied primary residences through this program. For HUD-code manufactured homes placed on land, see our land-home package loans.

Do I need an LLC to get a new construction loan?

An LLC or corporate entity is required for new construction loans. Most builders operate through an entity for liability protection and tax purposes, and we close in the name of your LLC or corporation. We recommend consulting with an attorney about entity structure before beginning a construction project.

What are the costs of a new construction loan?

New construction loans start at 10% interest-only with origination points and standard closing costs. Interest is calculated only on the drawn balance, meaning you do not pay interest on construction funds until they are released through the draw process.

Can I convert my construction loan into a rental loan after the build is complete?

Yes. If you decide to hold the completed property as a rental rather than selling it, you can refinance out of the construction loan into a long-term DSCR rental loan once a certificate of occupancy is issued and a tenant is in place. Requity supports both the construction and the permanent financing, allowing you to transition from build to hold without changing lenders.

Can I extend my construction loan if the build takes longer than expected?

Yes. Extension options are available if your construction timeline extends beyond the original loan term. Extensions are evaluated on a case-by-case basis and depend on project progress, remaining work, and market conditions. We recommend communicating early if you anticipate needing additional time so we can discuss options well before maturity.