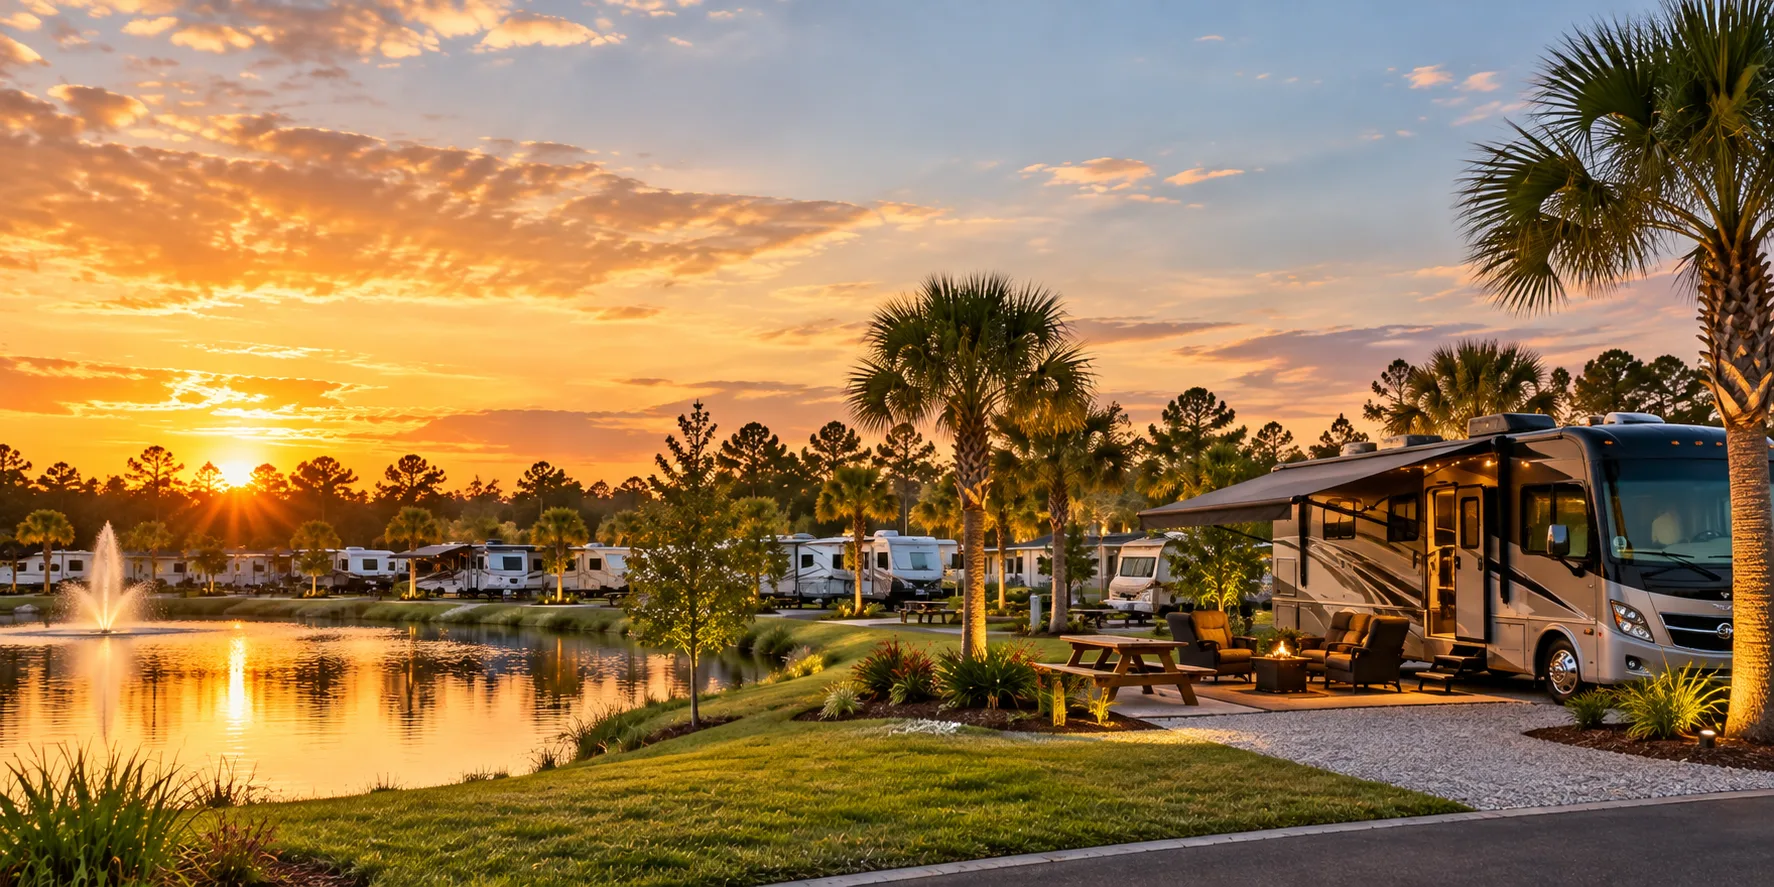
RV resort with lakeside campsites and palm trees at sunset

Loans › RV Park & Campground Loans

RV Park & Campground Loans

RV park & campground financing

Bridge loans for RV parks, campgrounds, and outdoor hospitality properties. Acquisition, expansion, and improvement capital from a lender who understands seasonal assets.

Close in as fast as 72 hours

Up to 75% loan-to-cost

Expansion capital available

Get your RV park loan quote

Term sheet in 24 hours. No obligation.

No credit pull required. Your information is secure.

$100K+

Loan size

Up to 75%

Loan-to-cost

10-12% IO

Rate

12-24 mo

Term

72 hrs

Fastest close

Available

Expansion capital

All loans are subject to underwriting approval. Rates, terms, and fees vary based on property type, loan-to-value ratio, borrower experience, and market conditions. Requity Lending is a commercial bridge lender; we do not offer consumer residential mortgages. Contact us for a customized quote.

Financing Options

Bridge loan vs. SBA loan for RV parks

Most RV park lenders on the market are SBA lenders. SBA 7(a) and 504 loans have the lowest rates available for RV parks, but they are slow, document-heavy, and require stabilized income history. Bridge financing exists for everything SBA cannot do: buying in the off-season, parks without clean financials, expansion projects, and deals that need to close in weeks. Many of our borrowers use both: bridge to acquire and stabilize, then refinance into SBA 504 or bank debt.

Bridge (Requity) SBA 7(a)/504
Typical rate 10-12% interest-only Lower, tied to Prime/Treasuries
Time to close 72 hours to 15 business days 60-120 days
Income documentation Underwritten to business plan 2-3 years stabilized history preferred
Best for Off-season acquisitions, value-add, expansion Stabilized parks, owner-operators holding long term

Why Requity

The RV park lender who understands seasonal assets

We Understand Seasonal Underwriting

RV parks do not produce even cash flow across 12 months. Our underwriting models account for seasonal revenue patterns, occupancy cycles, and the impact of weather on operations. We do not penalize properties for having an off-season.

Outdoor Hospitality Expertise

We evaluate RV parks and campgrounds differently than traditional commercial real estate. Site count, hookup types, amenity packages, and rate per night matter more than traditional NOI metrics for transitional properties.

Off-Season Acquisition Timing

The best RV park deals close in the off-season when sellers are motivated and competition is lower. A bridge loan that closes in as fast as 72 hours lets you acquire in winter and have the property ready for spring revenue.

Use Cases

RV park and campground financing use cases

From straightforward park acquisitions to expansion projects with new site development and amenity packages.

01

Park Acquisitions

Acquire RV parks and campgrounds that need operational improvements, site additions, or infrastructure upgrades. We underwrite to the stabilized potential, not just trailing revenue, which is critical for seasonal properties with inconsistent income histories.

02

Value-Add Repositioning

Finance the acquisition and improvement of underperforming parks. Add full hookup sites, upgrade electrical from 30 to 50 amp, improve roads, and add amenities that command premium nightly rates. Bridge capital covers both the purchase and the improvement budget.

03

Infrastructure Upgrades

Fund utility system upgrades, road improvements, bathhouse construction, Wi-Fi installation, and dump station additions. These improvements directly increase occupancy, average daily rates, and property value.

04

Expansion & Site Addition

Finance the development of additional RV sites, glamping units, cabins, or tent sites on existing park acreage. A vacant acre that generates $0 can produce $30-80,000 annually once developed with 8-10 sites.

05

Seasonal Cash Flow Bridges

RV parks in seasonal markets generate the majority of revenue in 4-6 months. Bridge financing provides capital to acquire and improve during the off-season so the property is optimized before peak season arrives.

06

Portfolio Consolidation

Combine multiple RV park or campground acquisitions into a single bridge facility. Operators building a portfolio of outdoor hospitality assets can streamline closings and reduce transaction friction.

FAQ

RV park loan FAQ

Does Requity Lending finance RV parks and campgrounds?

Yes. RV parks, campgrounds, and outdoor hospitality properties are an active lending category for Requity. We finance acquisitions, expansions, infrastructure upgrades, and value-add repositioning for these properties.

What are current RV park loan rates?

Requity bridge loans for RV parks and campgrounds currently range from 10% to 12%, interest-only for the full term, with a 2% origination fee. Pricing depends on property quality, seasonality profile, leverage, and borrower experience.

Can I get an SBA loan for an RV park?

Yes. SBA lenders offer the lowest rates available for RV parks, and SBA 7(a) and 504 loans are a strong fit for stabilized parks with documented income history. The trade-off is speed and paperwork: SBA loans are document-heavy and typically take 60 to 120 days to close. Many of our borrowers use bridge financing to acquire and stabilize a park, then refinance into SBA 504 or bank debt once the income history supports it.

How does Requity underwrite seasonal RV park income?

We evaluate RV parks based on their full annual revenue cycle, not just a single month or trailing quarter. Our underwriting accounts for peak season occupancy and rates, shoulder season performance, off-season baseline revenue, and year-over-year trends. We do not penalize a property for generating 60-70% of its revenue in 4-6 months if the annual cash flow supports the loan.

Can I get expansion capital included in my RV park bridge loan?

Yes. We structure improvement and expansion holdbacks directly into the bridge loan. This capital can fund new site development, utility upgrades, amenity construction, and infrastructure improvements. Funds are released through a draw process as work is completed.

Do you finance campgrounds and glamping properties?

Yes. We finance campgrounds, RV resorts, and glamping and outdoor hospitality properties. If you are evaluating the space, start with our guide to the glamping industry.

What is the typical exit strategy for an RV park bridge loan?

Common exits include refinancing into a conventional commercial loan or SBA 504 loan once the property is stabilized with documented income history, sale of the improved asset, or recapitalization. The typical stabilization timeline for an RV park value-add is 12-24 months depending on seasonality and scope of improvements.

What size RV parks does Requity finance?

We finance RV parks and campgrounds starting at $100,000 with no stated maximum. This covers properties with 30 to 300+ sites and beyond. Both established parks needing repositioning and properties being converted to RV park use are eligible.

Does Requity finance campground conversions or ground-up RV park development?

We finance value-add improvements and expansions on existing RV parks and campgrounds. For ground-up development projects, we evaluate on a case-by-case basis depending on entitlements, site plan, and operator experience. Submit your deal for a preliminary evaluation.

How fast can Requity close on an RV park acquisition?

We can close RV park acquisitions in as fast as 72 hours from signed term sheet. Most outdoor hospitality deals close within 72 hours to 15 business days. We deliver term sheets within 24 hours of receiving a complete deal package.

Are there specific markets where Requity focuses for RV park lending?

Requity Lending provides RV park and campground financing nationwide. We evaluate each market based on tourism demand drivers, proximity to attractions or natural destinations, seasonal traffic patterns, and comparable park performance in the area.