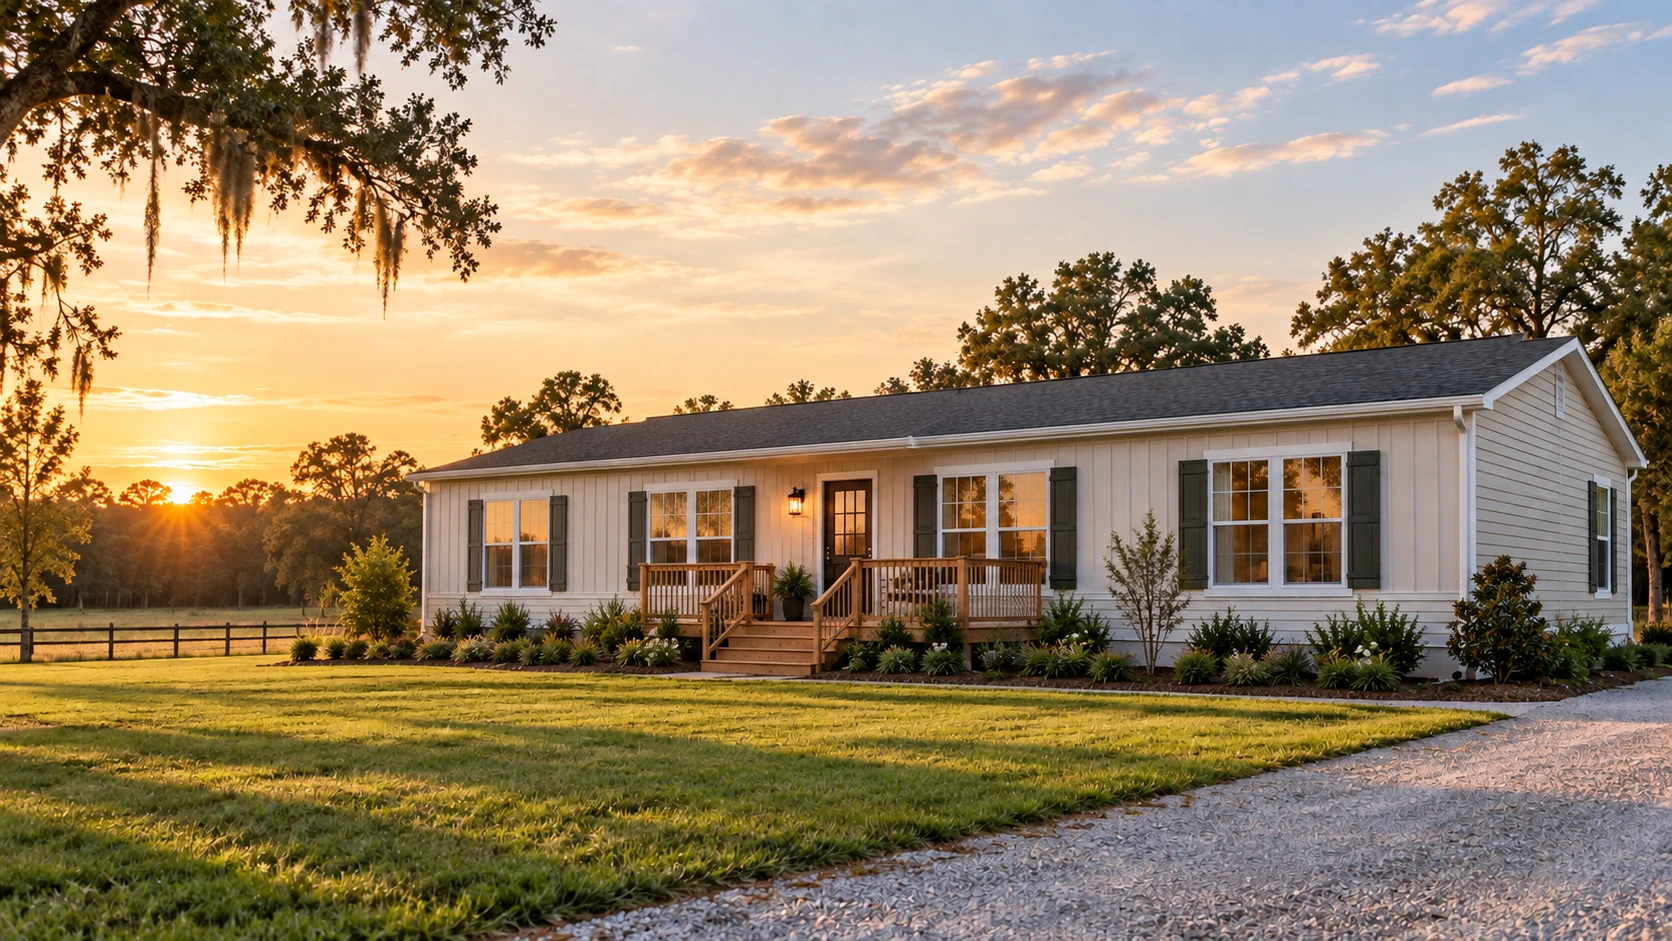
New manufactured home on a rural land parcel at sunset

Loans › Land-Home Package Loans

For Investors, Builders, and Operators

Land-home package loans for real estate investors

Business-purpose financing to buy land, place a new manufactured home on it, and sell or rent the finished property. One loan can cover the parcel, the home, delivery and setup, and site work, subject to underwriting.

Business-purpose financing

Land, home, setup, and site work

Up to 80% loan-to-cost

Submit your land-home deal

Our lending team will review the project and follow up with next steps.

Your information is secure.

Loan Program Details

Program details

Loan purpose

Business purpose only

Occupancy

Non-owner-occupied

Property

New manufactured home on land

Costs covered

Land, home, setup, and site work

Leverage

Up to 80% loan-to-cost

Borrower

LLC or business entity

Rates and terms

Quoted per deal

Requity Lending originates business-purpose loans secured by non-owner-occupied investment property. These are not consumer loans and are not for personal, family, or household use. All loans are subject to underwriting approval, and the costs financed, leverage, rate, and term are set deal by deal. A term sheet is not a commitment to lend.

Who It's For

Investor projects, not home mortgages

These are manufactured home construction loans for investors: short-term capital to create a finished, titled home on its own land, then exit. If you plan to live in the home, this is the wrong loan.

A fit if you are

Investors, builders, and operators buying land and placing a new manufactured home on it

Homes built to be sold to an end buyer or held as a rental

Borrowing through an LLC or other business entity

Non-owner-occupied projects only

Not a fit for

Buying a home you or a family member will live in

Consumer chattel (home-only) loans

Financing a mobile home park or community (see our mobile home park loans)

Modular or site-built homes (this program is for HUD-code manufactured homes)

How It Works

A typical land-home project

Most projects follow the same sequence from raw parcel to a home that can be sold or rented.

01

Tie up the parcel

Put a lot or acreage under contract and confirm that zoning allows a manufactured home, the minimum size or foundation rules, and that power, water, and sewer or septic are workable.

02

Order the home

Select a model from a dealer or manufacturer and get a written quote with the floor plan, section count, and what the dealer includes (delivery, set, trim-out, A/C, steps).

03

Prepare the site

Clearing, grading, driveway, well or water tap, septic or sewer tap, electric service, and the pad or foundation, all permitted locally before the home arrives.

04

Deliver and set

The home is transported, set on the foundation, anchored, and joined (for multi-section homes). Utilities are connected and skirting, decks, and steps are installed.

05

Final inspection

The local building department signs off and issues a certificate of occupancy or equivalent. Title work treats the home and land together as real property where state law allows.

06

Sell or rent

List the finished home for sale, or lease it and refinance into a long-term rental loan.

What Can Be Financed

Costs that may be financed, subject to underwriting

Financing manufactured home placement on land means paying for more than the home. We look at the full project budget. What we fund, and how much of it, is set in your term sheet.

01

Land

Purchase of the lot or acreage the home will sit on.

02

The home

Dealer or manufacturer price for the new manufactured home.

03

Delivery, set, and install

Transport, setup, anchoring, marriage line work on multi-section homes, and skirting.

04

Foundation

Piers, runners, or a permanent foundation system as required by the county or end-buyer financing.

05

Utilities

Well or water tap, septic or sewer tap, and electric service to the home.

06

Site work

Clearing, grading, driveway, drainage, permits, and local impact or tap fees.

Deal Package

What we need to review a deal

Send what you have. A complete package gets a faster, firmer answer, but you do not need every item to start the conversation.

Land purchase contract (or deed, if you already own the parcel)

Dealer or manufacturer quote with model, size, and what is included

Site work budget with contractor bids (utilities, foundation, driveway, clearing)

Survey, plat, or parcel map showing access and setbacks

Zoning confirmation that a manufactured home is allowed on the parcel

Utility plan: well and septic feasibility or perc test, or public tap availability

Exit plan with sales comps for the finished home, or a rent estimate if you plan to hold

Your entity documents and a summary of prior projects

Property and Title

What to check before you buy the land

Most land-home problems start with the parcel or the paperwork, not the home. Requirements vary by state and county.

Zoning and land use

Many counties and towns restrict where manufactured homes can go, set minimum square footage or roof pitch, or require a permanent foundation. Confirm this before you close on the land.

Title and real property status

When a new home leaves the factory it has a certificate of origin, similar to a vehicle. Most states have a process to affix the home to the land and retire or surrender that title so the home and land are treated as one piece of real property. Rules vary by state, and the title company handles the filing.

Access, flood, and restrictions

Check for legal road access, delivery clearance for the home, flood zone status, easements, and any HOA or deed restrictions that prohibit manufactured homes.

How Your Loan Works

You put in the first 20%. We fund the rest.

The loan covers up to 80% of total cost: land, home, setup, and site work. You bring the first 20% plus closing costs at closing. From there we fund 100% of the approved budget, paid directly to the dealer and contractors as each stage is done.

01

Get a dealer contract

One price from the dealer that covers the home, delivery, and setup.

02

Confirm the lot works

Before closing, get a soil test for the septic and a county letter confirming a manufactured home is allowed.

03

Sign your term sheet

We review the land, the budget, and your exit, then set your total cost, loan amount, and draw schedule.

04

Bring your 20% to closing

Through the title company, you pay for the land and the home deposit (together, your first 20% of the project), plus closing costs.

05

Close and order the home

Our loan closes and is recorded, and the dealer orders your home. From here, we fund everything in the approved budget.

06

Permits, then site work

Once permits are issued, we pay contractors directly as each stage passes inspection, or reimburse you for completed, verified work.

07

Home delivery

When the home is on your lot, we pay the dealer directly in exchange for the home's certificate of origin.

08

Completion

After the county signs off and the home is titled with the land as real property, the final holdback is released.

Exit Strategy

Two ways out

Sell to an end buyer

Most buyers will use a mortgage, and their lender will typically require the home to be on a permanent foundation and titled with the land as real property. Plan the foundation and title work around your buyer's financing from day one, and use sales comps of similar manufactured homes on land, not site-built comps.

Rent and refinance

Lease the finished home and refinance into long-term financing sized on rent, such as a DSCR rental loan, subject to that program's guidelines for manufactured homes. Include a rent estimate in your submission if you plan to hold.

FAQ

Common questions about land-home package loans

Don't see your question? Call 813.338.1000 or email contact@requitygroup.com.

Ask about your deal →
What is a land-home package loan for investors?

It is a single business-purpose loan that finances an investor's purchase of land and the placement of a new manufactured home on it, including delivery, installation, foundation, utilities, and site work, subject to underwriting. The loan is repaid when the finished home is sold or refinanced into a rental loan.

Can I live in the home?

No. This is business-purpose financing for investment property. Neither the borrower nor a family member can occupy the home. If you are buying a manufactured home to live in, you need a consumer mortgage lender.

Do you finance modular homes?

This program is for manufactured homes built to the federal HUD code. Modular homes are built to state and local building codes and are generally treated as site-built construction, so they are not financed under this program. If you have a modular project, submit it and we will tell you whether another program fits.

Can the home go in a park or on leased land?

This program is structured around a home placed on land your entity owns or is buying, with the home and land financed together. If you want to finance a manufactured housing community itself, see our mobile home park loans.

Do you finance used or relocated manufactured homes?

Tell us the home's year, size, HUD label and data plate details, and condition when you submit the deal, and we will tell you whether it fits.

What happens with the home's title?

In most states the home's certificate of origin or title is retired or surrendered once it is permanently affixed to the land, so the home and land are recorded together as real property. The process and forms vary by state and are handled by the title company. We review the plan for this during underwriting.

Can I refinance into a rental loan after the home is finished?

If you plan to hold the home, include that in your exit plan. Once the home is complete, titled with the land, and leased, you can apply for long-term rental financing such as our DSCR loans, subject to that program's guidelines.

What should I have ready before I submit a deal?

The land contract, the dealer's quote for the home, a site work budget with bids, zoning confirmation, and your exit plan with comps. Missing items do not stop you from submitting, but a complete package gets a faster answer.

Related Programs

Other ways we finance investors

New Construction Loans

Ground-up residential construction for investors.

Fix and Flip Loans

Acquisition and renovation of existing homes.

DSCR Rental Loans

Long-term rental financing based on property cash flow.

Mobile Home Park Loans

Financing for manufactured housing communities.